You can materially control theta decay by choosing the right expirations, using defined-risk premium-selling strategies, sizing positions appropriately, and following clear adjustment rules. Every short option you sell takes on short-volatility and short-gamma risk in exchange for that daily decay, so the payoff only holds up when you size it correctly. The sections below walk through the mechanics, the strategies, and the monitoring habits that turn theta from a mystery into a manageable input.
TL;DR:
- Theta accelerates near expiration, especially in the final week; at the money options usually have the most daily decay, while longer expirations carry more vega.
- Credit spreads and condors define maximum loss, while calendars and diagonals target faster decay in near term options against slower decay in longer dated contracts.
- Set a fixed cap on portfolio theta as a share of account value, then roll or close using preset time, profit, or delta triggers.
- Track net theta alongside delta, gamma, and vega; earnings, major economic releases, and expiration weeks can let volatility or price moves overwhelm daily decay.
- A theta reading of negative 0.05 implies about $5 in daily decay on one standard contract covering 100 shares, assuming price and volatility remain unchanged.
Table of Contents
- Refresher: Theta and the Greeks You Need to Know
- How Theta Behaves Across Strikes, Expirations, and Volatility
- Practical Theta-Management Strategies for Every Market View
- Position Sizing and Adjustment Rules for Theta Exposure
- Measuring and Monitoring Theta Day to Day
- Applying Decision Intelligence to Theta Management
- What Disciplined Traders Do Differently With Theta
- Another Way to Manage Theta Decisions: EI ALGOS
- FAQ
- Sources
Refresher: Theta and the Greeks You Need to Know
Theta measures how much an option's value drops each day, all else held equal. Theta indicates the position loses a small amount per day from time decay alone, as illustrated in an example Investopedia uses to show how the number translates into real dollars on your position. Theta is generally negative when you're long an option and positive when you're short one, which is the whole logic behind premium-selling: you collect what the buyer loses, according to the options primer from FINRA.
Decay isn't a straight line. It accelerates as expiration approaches, with the steepest drop showing up in the final 30 days and an even sharper pickup in the last week, per the options disclosure document published by the OCC, which describes options as "wasting assets." That's why a 45-day option and a 5-day option with similar strikes can have wildly different daily decay, even if their total extrinsic value looks similar on day one.
Theta doesn't act alone. It moves alongside delta, gamma, and vega, and reading one Greek in isolation leads to bad decisions:
- Delta measures directional exposure and shifts as the underlying moves.
- Gamma measures how fast delta changes, and it's highest in short-dated, at-the-money options, the same ones with the fastest theta.
- Vega measures sensitivity to implied volatility, which can swing your position's value far more than theta in a single day.
For a deeper walkthrough of how these four Greeks interact in practice, our guide to reading options Greeks breaks down real number checks you can run before placing a trade.
How Theta Behaves Across Strikes, Expirations, and Volatility
Not all theta is created equal. Where your strike sits relative to the stock price, how far out your expiration is, and what implied volatility is doing all change how much time decay you're actually dealing with.
- At-the-money options carry the most extrinsic value, so they typically show the largest daily theta of any strike at a given expiration, per Investopedia.
- Deep in-the-money and far out-of-the-money options carry less time value relative to their price, so their daily theta is smaller in dollar terms.
- Longer-dated options decay more slowly per day but carry more vega, meaning a move in implied volatility can matter more than the clock.
- Short-dated options decay fast and get faster, which is exactly why the final 30 days draw so much attention from premium sellers.
A theta of −0.05 on a single option means an estimated $5 loss per day on one standard 100-share contract if nothing else changes, based on the per-day example from Investopedia. That's a useful gut check before sizing any position: multiply your per-contract theta by your contract count and you get a rough daily burn rate.
Volatility complicates the picture. Higher implied volatility inflates premiums and, with them, the absolute dollar value of theta, but a volatility spike or a sharp price move can easily swamp a day's decay in either direction. A trade with attractive-looking theta can still lose money on a day when volatility expands faster than time erodes value.
One detail traders often miss: theta decay runs on calendar days, not just trading days. Pricing models generally account for weekends and holidays in the decay calculation, so a Friday close typically shows some of Saturday's and Sunday's decay baked in rather than a dead weekend, a point Investopedia notes when describing how theta accrues across a full seven-day week.
Practical Theta-Management Strategies for Every Market View
Once you understand how theta moves, the next step is picking a structure that matches your view and your risk tolerance. Here are the core approaches traders use to put theta to work instead of being surprised by it:
- Short OTM verticals (credit spreads): Selling a vertical spread collects premium while defining your maximum loss, making it a practical choice when you have a directional lean or a neutral-to-mild view and want theta working in your favor without naked exposure.
- Iron condors and iron butterflies: These combine two credit spreads to collect premium on both sides of the current price, suiting range-bound, lower-volatility conditions. Wider strikes raise your probability of profit but shrink the credit collected, so the width you choose is a direct trade-off between theta income and win rate.
- Calendar and diagonal spreads: Selling a near-term option against a longer-dated option in the same name exploits the fact that near-term contracts decay faster than longer-dated ones, letting you collect theta on the front leg while holding slower-decaying exposure further out.
- Covered calls and collars: Selling calls against stock you already own monetizes theta while keeping your equity exposure; adding a protective put turns the structure into a collar that caps both your upside and your downside.
- Long-dated options (LEAPS) for directional exposure: Buying further-out expirations reduces your daily theta burn when you want sustained directional exposure without the decay pressure that comes with shorter-dated calls or puts.
A few supporting points worth keeping in mind as you pick among these:
- Defined-risk structures (spreads, condors) cap your loss if volatility expands against you.
- Undefined-risk, short-premium trades carry theoretically larger loss potential and need tighter position sizing.
- Mixing expirations (calendars, diagonals) lets you isolate the decay differential rather than betting on direction alone.
Here's a simple numeric illustration. Say you sell a 30-day iron condor collecting $1.20 in total credit, and the position carries a combined theta of −$0.04 per day across both spreads. If the stock stays range-bound and volatility holds steady, theoretical decay works in your favor each day, accumulating toward the total credit as expiration nears, assuming nothing else moves against you. That's an illustrative example only, not a guaranteed outcome, since gamma risk grows as expiration approaches and a late move can erase days of accumulated decay quickly.
Pro Tip: Match your structure to your view first, then check theta, rather than chasing the trade with the biggest theta number regardless of what the position actually requires if the market moves against you.
Position Sizing and Adjustment Rules for Theta Exposure
Strategy selection only works if you size and manage positions consistently. Most costly theta mistakes come from oversized exposure or indecision when a trade moves against you, not from a flawed strategy itself.
Start with a sizing cap. A practical approach is limiting your aggregate theta exposure, in dollars per day, to a fixed percentage of your account, then tracking it as you add positions so one large trade doesn't dominate your daily risk. Our breakdown of sizing trades with a risk graph walks through how to translate that percentage into actual contract counts.
Rolling versus closing comes down to a few repeatable triggers rather than gut feel:
- Time-based trigger: Many traders roll or close once a short option reaches a set number of days to expiration, since gamma risk accelerates in that window.
- Profit-based trigger: Closing once a large share of the maximum credit has been captured locks in the bulk of the gain without holding through the riskiest final days.
- Delta-based trigger: A short strike that's drifted to a materially higher delta than when you opened the trade signals rising assignment risk and often warrants a roll.
Build a short pre-trade checklist covering when you'll roll, when you'll hedge with the underlying or an offsetting option, and when you'll simply accept assignment rather than paying up to avoid it. Our trade adjustments checklist and our detailed guide on when to roll options both lay out specific timing rules you can adapt into your own plan.
For larger short-theta portfolios, delta-hedging or gamma-aware adjustments, buying or selling shares or offsetting options to neutralize directional exposure, are standard techniques for keeping a theta-collecting book from turning into an accidental directional bet, a dynamic described in the delta-gamma-theta framework from the University of Illinois.

Pro Tip: Write your roll and hedge rules down before you open the trade, not while you're staring at a position that's already moved against you.
Measuring and Monitoring Theta Day to Day
Managing theta well means checking it on a routine, not just when something feels off. Start by computing your portfolio's net theta in dollars per day, summing the theta of every open position, so you know your total daily decay exposure at a glance rather than estimating it trade by trade.
Your broker's Greeks panel or a risk graph should show four numbers worth checking daily:
- Net theta, your total expected daily decay or gain.
- Net delta, your overall directional exposure.
- Net gamma, how fast that delta can shift.
- Vega exposure, your sensitivity to implied volatility changes.
| Check | What to watch | Why it matters |
|---|---|---|
| Net theta | Total $/day across all positions | Confirms your aggregate decay matches your risk budget |
| Net gamma | Concentration near short-dated strikes | Flags rising assignment and whipsaw risk |
| Vega exposure | Sensitivity ahead of earnings or macro events | Warns when a volatility event could overwhelm theta |
| Expiration week | Days remaining on short options | Signals when gamma risk accelerates sharply |
Event-driven checks matter as much as the daily numbers. Earnings dates, major macro releases, and expiration weeks are the moments when gamma and vega can dominate theta, so it's worth flagging those dates on every position the week you open it. A simple spreadsheet tracking per-position theta alongside your broker's risk graph is often enough to catch a drifting position before it becomes a problem.
Applying Decision Intelligence to Theta Management
Reading the Greeks correctly is only half the job. The other half is how consistently you act on what you see, and that's where most theta-related losses actually happen. We built our six-factor decision score to catch the setups where the numbers look fine but the behavioral context doesn't, flagging oversized trades or impulsive entries before they turn into the kind of theta trade that gets ignored on day three of a loss.
Our LIANA assistant adds a layer of personalized feedback on top of that score. It can nudge you when a theta-heavy position has drifted past your own stated roll point, or when your recent pattern shows you've been holding short options longer than your own rules allow.
- Behavioral scoring flags sizing drift before it compounds into a larger theta exposure problem.
- LIANA's nudges are personalized to your own trade history, not a generic alert.
- Reviewing closed trades through a structured workflow, like the one in our trade analysis guide, helps you see whether your rolling decisions were rules-based or reactive.
Numeric Greeks tell you what your position is exposed to. Behavioral signals tell you whether you're likely to follow your own plan when that exposure changes.
What Disciplined Traders Do Differently With Theta
The traders who struggle with theta usually share the same habits: oversized long options bought without a time budget, rolling short positions reactively instead of on a pre-set trigger, and ignoring vega until a volatility spike erases a week of decay. The fix isn't more Greeks knowledge, it's fewer live decisions made under pressure. Write your roll and size rules before you open the trade, keep a short daily theta log, and enforce a hard size cap even when a setup looks attractive. Try holding yourself to one new rule for a month and track whether your results get steadier before adding a second.
— Anantha
Another Way to Manage Theta Decisions: EI ALGOS
Reading Greeks correctly solves half the theta problem. The other half is whether you actually follow your own sizing and rolling rules once a position starts moving, and that's the gap our platform is built to close. Rather than generating signals or forecasts, we score each setup through a six-factor decision engine that flags sizing drift, oversized theta exposure, and reactive rolling before they turn into bigger losses.
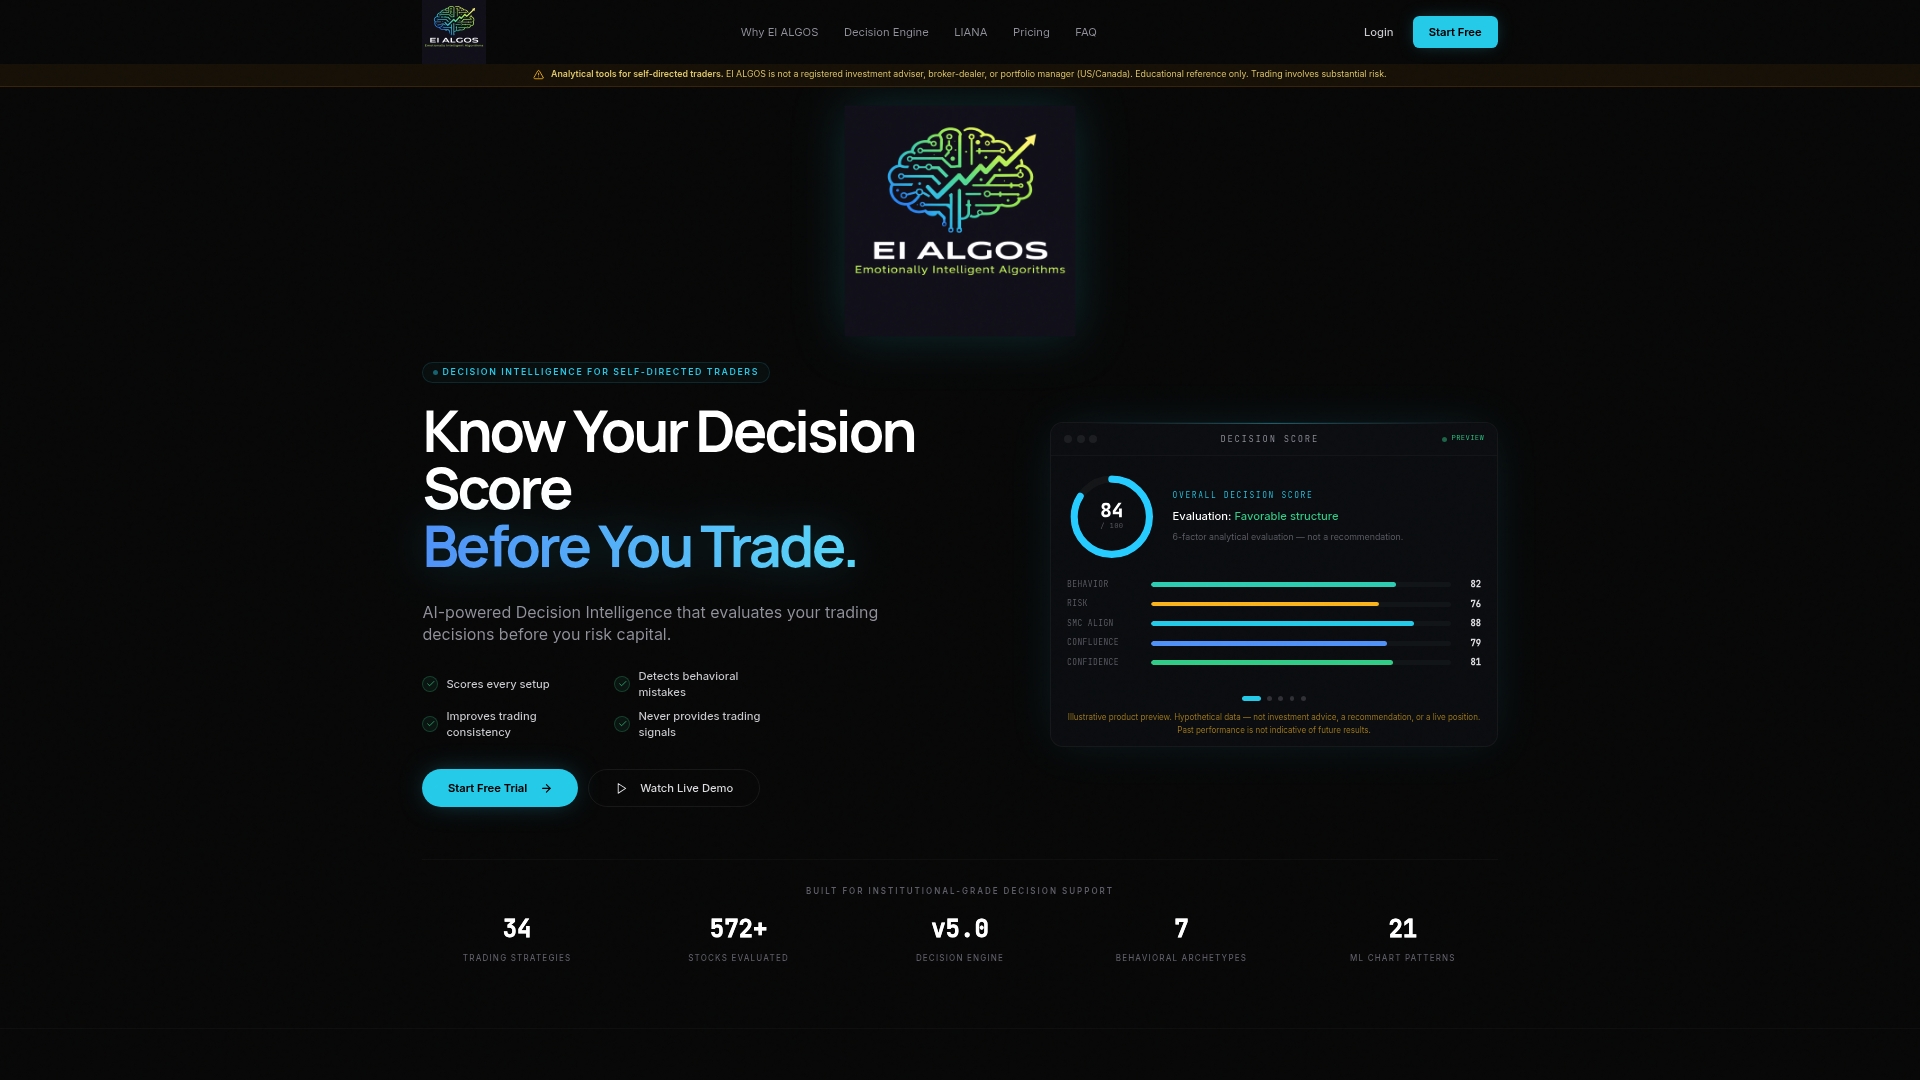
- Our decision score evaluates the behavioral context behind a trade, not just its Greeks.
- LIANA, our AI assistant, delivers personalized nudges based on your own trading history and past rolling patterns.
- Our trade-review workflows help you compare what your rules said against what you actually did.
This complements your existing Greeks checks rather than replacing them: you still watch theta, delta, and vega on your broker's risk graph, and a behavioral decision layer can be added on top. Our Free plan is a practical starting point if you want to see how decision scoring applies to your own theta trades.
FAQ
How much theta decays in one day?
Theta expresses the estimated dollar loss an option's value absorbs over a single day, so a theta of −0.05 means roughly $0.05 per contract share, or about $5 on a standard 100-share contract, per Investopedia. That figure changes daily, growing larger in magnitude as expiration approaches.
Is higher or lower theta better?
It depends on which side of the trade you're on. A seller generally wants higher theta working in their favor as decay accelerates, while a buyer of options wants lower theta so their position loses less value to time, a distinction FINRA draws between long and short option positions.
What is the best theta options strategy?
There isn't a single best strategy since the right choice depends on your market view and risk tolerance. Defined-risk approaches like credit spreads and iron condors are common choices for collecting theta in range-bound or mildly directional markets, while calendars and diagonals target the decay differential between near-term and longer-dated contracts.
Is negative theta on a call option bad?
Negative theta on a long call simply means the option loses value each day as time passes, which is expected for any purchased option and not inherently a flaw in the trade. It becomes a problem only when the underlying fails to move enough, or quickly enough, to offset that decay before expiration.
Sources
- Options disclosure document — OCC
- Finra
- Theta definition — Investopedia
- University of Illinois — Chapter 5 (Greeks & approximations)