The Sharpe ratio tells you how much return you earned for each unit of risk you took. You subtract the risk-free rate from your return, then divide by the standard deviation of your returns. A higher number means more reward per unit of volatility. It does not tell you why you earned it, and for a self-directed trader that "why" is the part you can actually change.
This guide covers the formula, a worked example, how to annualize it from daily or monthly data, what counts as a good number, and where the ratio misleads. It also shows how to pair it with a review of your decisions, because the ratio only measures outcomes.
TL;DR
- The Sharpe ratio is excess return divided by the standard deviation of returns: reward per unit of total volatility.
- Compute it on periodic returns (monthly or daily), then annualize by multiplying by √12 or √252.
- There is no universal "good" number. Compare it to a benchmark or to other strategies, and look at how long the track record is.
- It treats upside and downside swings the same and assumes roughly normal returns, so it can flatter or punish the wrong strategies.
- It scores results, not choices. Reviewing the quality of each decision tells you what to fix when the ratio drops.
Table of Contents
- What the Sharpe ratio measures
- The formula
- A worked example
- How to calculate it from your own trades
- What is a good Sharpe ratio for trading?
- Using the Sharpe ratio to compare strategies
- Where the Sharpe ratio misleads
- The gap the ratio cannot close: your decisions
- Put decision quality next to your Sharpe ratio
- FAQ
- Sources
What the Sharpe ratio measures
A CFA Institute newsletter describes the Sharpe ratio as the portion of performance associated with risk-taking relative to total risk. A risk-free portfolio, or one with zero excess return, has a ratio of zero.
Two traders can both make 20% in a year. If one did it with small, steady monthly gains and the other with violent swings that happened to end up positive, the first has the higher Sharpe ratio. That is the point of the metric: it asks whether your return was worth the ride.
The ratio is a relative measure. OpenStax's finance text notes there is no absolute number that says performance is good or bad. You judge it against other managers, strategies or a benchmark index.
The formula
The standard form, as given in OpenStax Principles of Finance, is:
Sharpe ratio = (Rp − Rf) / σp
- Rp is the average return of your portfolio or strategy.
- Rf is the risk-free rate, usually a short-term Treasury yield for US traders.
- σp is the standard deviation of your returns, which is how widely they scatter around their average.
The top of the fraction is your excess return, what you earned above a no-risk alternative. The bottom is the volatility you accepted to get it.
The risk-free rate moves with Federal Reserve policy and Treasury yields, so use the figure for the same period as your returns. Pull it from the Treasury's published yield tables for the months you are measuring, not from memory.
A worked example
OpenStax gives a clean US example: a 3% risk-free return and a 20% portfolio return leave a 17% excess return. With a standard deviation of 26%, the Sharpe ratio is 17% / 26% = 0.65.
Now compare two strategies. A practice note from SLCG shows that an investment with a 12% mean excess return and 20% standard deviation has a Sharpe ratio of 0.6, against 0.5 for one with 15% and 30%. The second strategy earns more, yet it pays less per unit of risk. If you could size the first strategy up, it would be the better engine.
That is the practical use: ranking strategies fairly when their raw returns are not comparable because their volatility differs.
How to calculate it from your own trades
- Choose a return period. Sharpe recommended measuring returns and risk over short intervals such as months, then annualizing. Use monthly or daily account returns, including open-position changes if you hold overnight.
- Subtract the risk-free rate for the same period from each return.
- Average the excess returns.
- Compute the standard deviation of those excess returns. A spreadsheet's STDEV function does this.
- Divide the average by the standard deviation.
- Annualize.
Annualizing
Berkeley's Robert Harvey states that with N return observations per year, the annualized Sharpe ratio is (μ/σ) × √N. That means √12 for monthly returns and √252 for daily returns, since a year has about 252 trading days.
Example with monthly data: your average monthly excess return is 1.0% and the standard deviation is 4.0%. The monthly ratio is 0.25. Multiply by √12 (about 3.46) and the annualized Sharpe ratio is about 0.87.
Example with daily data: an average daily excess return of 0.08% and a daily standard deviation of 1.0% give 0.08. Multiply by √252 (about 15.87) and you get about 1.27.
The square-root rule rests on an assumption. An academic paper on common Sharpe errors points out that it requires daily returns to be independent and identically distributed, which is false in practice because of momentum, reversal and seasonality. Treat an annualized figure as an estimate, not a precise measurement. The same paper notes that the ideal sample would span decades, which no trader has, so daily or monthly data is the working compromise.

What is a good Sharpe ratio for trading?
Common rules of thumb sort 0 to 1 as low, 1 to 2 as good and 2 to 3 as very good. They are guides, not laws. A better reading depends on three things.
The benchmark. A 0.5 ratio is poor if a plain index fund delivered more over the same window. It is a reasonable result for a part-time strategy in a hard year. Compare against what you could have held instead.
The length of the record. Course notes from Rensselaer Polytechnic Institute say that about three years is an acceptable track record, and a Sharpe ratio of 2 or higher over more than three years is considered very good. A ratio of 7 over six weeks says almost nothing. It usually means a short, lucky run or too few data points.
The statistics. Harvey frames a t-statistic as the annualized Sharpe ratio multiplied by the square root of the number of years. A t-statistic near 2 is the usual bar for telling a result from zero. So an annualized Sharpe of 1.0 needs roughly four years of data to clear it, while 2.0 needs about one. Researchers Benhamou and colleagues build on this and publish tables of the minimum Sharpe ratio needed for significance given the time period and autocorrelation.
As a self-directed trader with a few months of history, your Sharpe ratio is a rough signal. Do not size up on it alone.
Using the Sharpe ratio to compare strategies
The ratio works best when you hold the measurement constant and change one thing:
- Same period, different setups. Compute it separately for breakouts and pullbacks, or for stocks and options trades, using the same return interval.
- Same strategy, different holding rules. See whether a tighter exit lowers volatility more than it lowers return.
- Same strategy, different months. A falling ratio flags that something changed, in the market or in you.
The last case is where the number stops helping. It says your reward per unit of risk fell. It does not say whether you widened stops, took oversized positions or chased entries. Our guides on risk-reward trading and trade management strategies cover the rules that most often move volatility and returns together.
Where the Sharpe ratio misleads
The CFA Institute newsletter lists the main weaknesses: the ratio measures only variance, assumes normally distributed returns, penalizes upside and downside volatility equally, and can be flattered by lengthening the measurement period. For traders, that has concrete consequences.
Big winners count as risk. A trend strategy that makes a few outsized gains has a high standard deviation, so the ratio can look mediocre even when the profit profile is what you want.
Hidden tail risk looks safe. A strategy that collects small gains and occasionally takes a large loss can post a high ratio for a long stretch. Selling options premium is the classic case. Returns of that shape are not normal, which the ratio assumes.
Serial correlation inflates it. The SLCG note cites research showing that positive serial correlation in hedge fund returns overstates annualized Sharpe ratios. Smoothed or stale pricing, and streaky trading, can do the same to a personal track record.
It is error-prone with small samples. Expected returns and volatility must be estimated from limited data, which is why the luck-or-skill research stresses statistical tests rather than raw readings.
Position size changes the picture. If your size creeps up after wins, the return stream you measure is no longer one strategy. These copy trading allocation methods show with spreadsheet examples how size drift distorts results, and the same logic applies to a manual account.

A practical response is to read the Sharpe ratio next to maximum drawdown, the distribution of your wins and losses, and your average risk per trade. Our piece on sizing trades to 1 to 2% covers keeping risk per trade consistent, which makes any ratio easier to trust.
The gap the ratio cannot close: your decisions
Suppose your Sharpe ratio drops from 1.4 to 0.7 over a quarter. The math will not tell you whether the cause is market regime, a changed setup, or behavior: revenge trades after a loss, early exits, skipped rules, oversized positions on conviction.
Those are decision errors, and they leave their marks on volatility and returns long before the ratio catches up. Our overview of behavioral trading explains how behavior drives retail results. The trader performance analysis guide goes beyond win rate. The article on how to stop overtrading addresses one of the most common sources of a falling ratio.
A simple routine helps:
- Compute your Sharpe ratio monthly, with the same method each time.
- When it falls, list the trades that contributed most to volatility and to losses.
- Check each against your written rules: setup quality, size, stop placement, exit.
- Fix the process fault, not the number.
The step-by-step guide to scoring every trade shows how to do step 3 before the trade, not after.
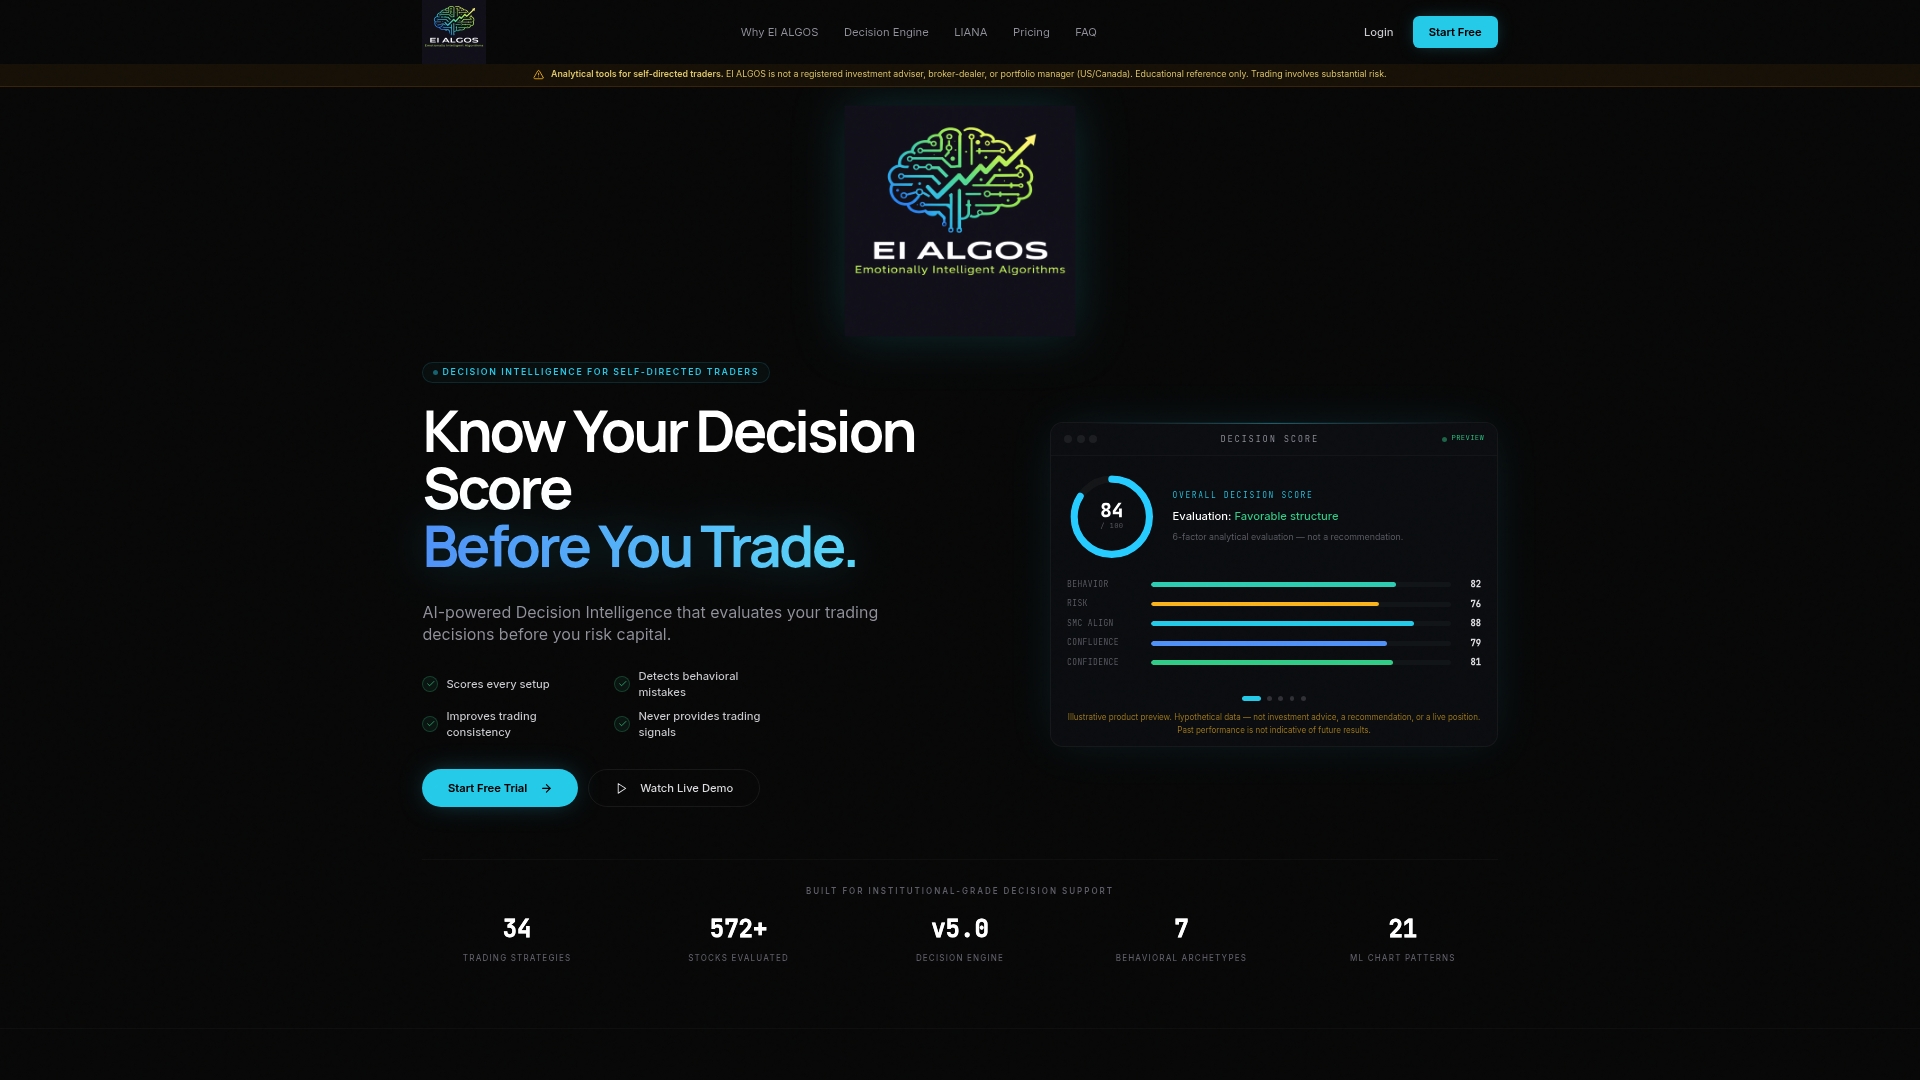
Our view: a performance ratio is a lagging report card. We built EI ALGOS around the idea that self-directed traders improve faster by examining the quality of each decision as it is made.
The platform scores every setup on a six-factor analytical engine and flags behavioral errors, so you see the cause of a weak month and not only its size. It does not issue trade signals or predictions. Its job is to help you understand your own patterns, and LIANA, our assistant, gives personalized feedback on your process over time.
Use Sharpe, drawdown and win rate to measure outcomes. Use decision scoring to change the behavior that produces them. When a trader's process is consistent, the ratios have a chance to follow.
Anantha
Put decision quality next to your Sharpe ratio
EI ALGOS is a web-based Decision Intelligence platform for self-directed traders. It scores each trade setup on six factors, detects behavioral errors, and gives you live trade management tools, options analysis and strategy pattern detection. You can start on the Free plan at $0 per month. Paid plans are Starter at $49 per month, Pro at $129 per month and Elite at $229 per month. Compare them on the EI ALGOS plans page, or see how the platform works first.
If you keep a journal, the AI-coached trading journal turns review into a routine, and LIANA gives feedback on the patterns in your trades.
FAQ
What is a good Sharpe ratio for trading?
As a rule of thumb, 1 to 2 is good and above 2 is very good, but only over a long enough record. Course notes from RPI describe 2 or higher over more than three years as very good. Always compare against a benchmark and the length of your sample.
Is a 0.5 Sharpe ratio good?
It depends on the benchmark and the period. A 0.5 is modest, and it beats a strategy at 0.4 over the same period. The SLCG practice note uses 0.5 and 0.6 as an example of how a small difference reflects reward per unit of risk. Judge it relative to your alternatives, not in isolation.
Is a Sharpe ratio of 7 good?
A figure that high usually signals a very short sample, smoothed returns or hidden tail risk, not exceptional skill. Test it with the t-statistic approach: multiply the annualized ratio by the square root of the years of data, and check that the record is long enough to mean something.
Should I use daily or monthly returns?
Either works if you stay consistent. Monthly returns are the traditional choice. Daily returns give more observations and are annualized with √252. Both rely on assumptions about independence that real returns only approximately meet.
Sources
- CFA Institute newsletter on the Sharpe ratio and the information ratio
- OpenStax Principles of Finance, 15.4 Applications in Performance Measurement
- SLCG Sharpe Ratio Practice Note
- Robert Harvey, Evaluating Trading Strategies (UC Berkeley)
- What is the Sharpe Ratio, and how can everyone get it wrong? (arXiv 1802.04413)
- Testing Sharpe ratio: luck or skill? (arXiv 1905.08042)
- Rensselaer Polytechnic Institute, Computational Finance: Optimal Trading